
Personal Finance
The weight of mounting debt can feel overwhelming. Juggling multiple creditors, facing high interest rates, and the constant stress of repayment deadlines can take a significant toll on individuals and businesses alike. In South Africa, many find themselves in this precarious position, seeking viable solutions to regain financial stability. One of the most common strategies is taking out loans to pay off debt. This approach, when understood and utilized correctly, can offer a much-needed lifeline, simplifying finances and paving a path towards a debt-free future.
This comprehensive article will delve into everything you need to know about loans to pay off debt, exploring their benefits, potential drawbacks, and crucial considerations. We will also introduce specialised financial products from NH Finance, a brokerage that provides access to diverse funding solutions, designed to assist South Africans in various circumstances to manage and overcome their debt burdens.
Understanding Loans to Pay Off Debt: A Double-Edged Sword?
The concept of using a new loan to settle existing debts – often referred to as debt consolidation – can be a powerful financial tool. The primary allure lies in several potential benefits:
- Simplified Repayments: Instead of managing multiple monthly payments to various creditors, a single consolidated loan means only one payment to track. This can significantly reduce administrative burden and the risk of missed payments.
- Potentially Lower Interest Rates: If you can secure a new loan with an overall lower interest rate than the average rate of your existing debts (especially high-interest debts like credit cards or store accounts), you could save a substantial amount on interest charges over the loan term.
- Reduced Monthly Instalments: By extending the repayment period with a new loan, the monthly instalment amount can often be reduced, easing immediate cash flow pressures. However, it’s crucial to remember that a longer term might mean paying more interest overall.
- Improved Credit Score (Long-Term): Responsibly managing a debt consolidation loan and ensuring timely payments can positively impact your credit score over time. Closing down old accounts (once settled) can also eventually be beneficial, though initial hard credit inquiries for new loans can temporarily dip your score.
- Avoiding Legal Action: For those struggling with arrears, a loan to pay off these pressing debts can help avoid potential legal action from creditors, such as judgments or garnishee orders.
However, it’s essential to approach loans to pay off debt with a clear understanding of the potential downsides:
- Extended Debt Period: While monthly payments might be lower, a longer loan term means you remain in debt for a more extended period.
- Fees and Costs: New loans often come with initiation fees, service fees, and potentially early settlement penalties on the debts you’re paying off. These costs must be factored into the overall benefit analysis.
- Risk of Further Debt: Securing a consolidation loan can free up credit on old accounts. Without a disciplined approach to spending, there’s a risk of accumulating new debt on top of the consolidation loan, worsening the situation.
- Not a Solution for Overspending: Loans to pay off debt address the symptoms of financial distress, not necessarily the root cause. If underlying overspending habits aren’t addressed, debt problems are likely to recur.
- Qualification Criteria: Securing a loan with favourable terms usually requires a reasonable credit record and proof of stable income. Those already deep in debt might find it challenging to qualify for beneficial options.
In South Africa, the National Credit Act (NCA) provides a regulatory framework for consumer credit, offering protections and ensuring fair practices from credit providers. It’s vital to deal with registered credit providers or reputable financial intermediaries.
Tailored Solutions for Debt Challenges
New Heights Finance operates as a finance brokerage in South Africa, connecting individuals and businesses with a panel of lenders and financial institutions. They specialise in sourcing and structuring various funding solutions, with a particular focus on leveraging property and other assets. For those specifically looking for loans to pay off debt, or alternative financial strategies to manage indebtedness, NH Finance offers several distinct products. It’s important to note that NH Finance acts as a broker and does not directly provide the loans or funding themselves but facilitates access to it.
Below, we explore five key offerings from NH Finance that can be instrumental when seeking ways to address significant debt:
1. Debt Consolidation Bonded Property
This NH Finance offering presents a distinctive method for homeowners to tackle substantial debt, particularly those who may not qualify for traditional loans to pay off debt due to their credit profile. It is not a loan in the conventional sense but rather a “Sell and Buy Back” agreement (also known as Sale and Leaseback).
Here’s how it generally works:
- Sell Your Property: You sell your property (residential, commercial, industrial, or retail with a minimum value of R1 million) to a third-party investor introduced via NH Finance’s network.
- Settle Debts: The proceeds from the sale are then used by you to settle your existing debts, effectively consolidating them. This solution welcomes all credit profiles.
- Rent Back: You enter into an agreement to rent the property back from the new owner for a negotiated period, typically between 12 to 24 months, allowing you to remain in your home or business premises.
- Buy Back Option: Crucially, the agreement includes an option for you to repurchase the property within the 12-24 month period at a price agreed upon at the outset.
This innovative solution is designed for property owners who need to release equity to clear significant debts and improve their financial standing. While it involves the temporary sale of the property, the buy-back clause offers a route to regaining ownership once finances have stabilised. NH Finance facilitates this by referring your enquiry to third parties who specialise in these transactions; neither NH Finance nor the third-party vendors are FSPs or registered with the NCR for this specific property transaction solution. The maximum debt amount typically considered is up to 50% of the property’s value.
Apply for debt consolidation using bonded property here
2. Business Rescue Using Property
For businesses facing financial hardship and undergoing formal Business Rescue proceedings, NH Finance offers access to specialised loans to pay off debt that are specifically tied to immovable property. This solution is tailored for Business Rescue Practitioners (BRPs) who need to unlock funds to facilitate the rescue plan.
Key features include:
- Target Audience: Aimed at legal entities that own bond-free (fully paid-up) property.
- Loan Purpose: The primary goal is to provide capital to settle outstanding property-related charges such as rates, taxes, and levies. This is often a critical step to enable the sale or transfer of properties as part of the rescue plan, thereby improving liquidity.
- Loan Conditions: Properties must typically be valued at over R1.5 million. Businesses can secure loans of up to 50% of the property’s open market value. These are short-term loans, usually with a term of 6 to 12 months.
- Interest Rates: Monthly interest rates generally range from 2.8% to 4%.
- Benefits: This funding can accelerate property transfers, prevent lost deals due to funding shortfalls for clearance costs, improve cash flow for the business under rescue, and ultimately reduce the recovery timeline.
NH Finance acts as a broker, connecting BRPs and distressed businesses with financial institutions that offer these specialised loans. This type of funding can be pivotal in turning illiquid assets into the cash needed to pay off company debts and contribute to a successful business rescue.
Apply for business rescue funding
3. Liquidators Finance
Similar to Business Rescue finance, Liquidators Finance is a specialised bridging loan product brokered by NH Finance. It is designed to assist liquidators who are managing the winding up of an insolvent estate. Delays in selling and transferring immovable properties can create significant cash flow challenges for liquidators, hindering their ability to cover ongoing administration costs and distribute funds to creditors. These loans to pay off debt (owed by the liquidated entity) help to smooth this process.
The product specifics are:
- Target Audience: Appointed liquidators of insolvent estates that include bond-free immovable property.
- Loan Purpose: To provide upfront cash, secured against the eventual sale proceeds of a property. This allows liquidators to cover essential holding costs (security, maintenance, insurance), pay for clearance figures (rates and taxes) to facilitate transfer, and potentially make interim distributions to creditors.
- Loan Conditions: Applicable to bond-free properties valued at over R1.5 million. Liquidators can generally access up to 50% of the property’s open market value. Loan terms are typically short, ranging from 6 to 12 months, aligning with the expected property sale timeline.
- Interest Rates: Monthly interest rates are in the region of 2.8% to 4%.
- Benefits: This financing prevents valuable property sales from collapsing due to a lack of immediate funds for transfer costs. It ensures a smoother, more efficient liquidation process, which can lead to better and faster returns for creditors.
By providing access to this type of finance, NH Finance helps liquidators unlock the value tied up in properties more quickly, facilitating the payment of the insolvent entity’s debts.
Apply for liquidators finance
4. Loans Against Property
For legal entities that own fully paid-up (unbonded) property, NH Finance brokers loans against property. This is a more general-purpose secured loan that can be an effective way to raise capital for various needs, including the crucial objective of settling existing business debts.
Key aspects of this offering:
- Eligibility: Available to legal entities (e.g., companies) that own bond-free commercial, industrial, or even personal property (if held in a legal entity). The property value typically needs to be over R1.5 million (though some references suggest R1 million may be considered – clarification with NH Finance is advised).
- Loan Amount: Borrowers can typically access up to 50% of the property’s open market value.
- Repayment Term: These are short-term loans, usually structured over 6 to 12 months.
- Interest Rate: Monthly interest rates generally fall between 2.8% and 4%.
- Versatile Uses: While the funds can be used for various business purposes such as cash flow injection, funding new contracts, or purchasing new property while awaiting a sale, a significant application is toclear existing business debts. This allows a business to consolidate multiple, perhaps higher-cost, debts into a single, property-backed loan.
- Security: The lender registers a bond over the property as security for the loan.
This type of loan offers a swift way for businesses to leverage their most valuable assets to restructure their finances, pay off pressing creditors, and improve their overall financial health.
5. Loans Against Assets
Beyond immovable property, NH Finance also facilitates access to loans against movable assets. This option provides a way for individuals or businesses to secure short-term cash advances quickly by using wholly-owned valuable items as collateral. This can be a vital resource when funds are needed urgently, including for settling immediate debts to avoid further complications.
Features include:
- Acceptable Assets: A wide range of paid-up movable assets can be considered, such as vehicles (cars, trucks, boats, yachts), jewellery (gold, diamonds), high-value art, luxury watches, antiques, and even business assets like equipment and stock.
- Loan Process: The process involves applying, receiving a quote based on the asset’s value, lodging the asset with the lender as security, and then receiving the funds. The asset is returned upon full settlement of the loan.
- Loan Amount: Typically, one can borrow up to 70% of the asset’s assessed value. Loan amounts can range from R50,000 up to R20 million.
- Term and Cost: These are short-term loans, generally for 3 to 6 months, though terms can be shorter or longer and potentially renewable. The cost includes a monthly interest rate (indicated around 5% on the NH Finance page, though APR examples vary and should be confirmed directly with the lender) plus an initiation fee.
- Speed and Accessibility: A key advantage is the speed of processing, with payouts possible within a day. This is particularly useful when traditional bank loans are not an option or would take too long to secure, especially when facing urgent demands from creditors.
- No Credit Checks (Typically): The loan is secured by the asset, so credit history is often less of a barrier compared to unsecured loans.
These loans to pay off debt are particularly suited for situations requiring immediate liquidity where the borrower has valuable assets they can temporarily pledge. The funds can be used at the borrower’s discretion, including for consolidating smaller, troublesome debts.
Choosing the Right Loans to Pay Off Debt
Deciding to take a loan to pay off existing debt, or opting for an alternative like a sale-and-leaseback agreement, is a significant financial step. It’s not a decision to be taken lightly. Here are some crucial considerations:
- Assess Your Entire Financial Situation: Understand the full extent of your debt, your income, expenses, and the reasons you fell into debt.
- Calculate the True Cost: Don’t just look at the interest rate. Factor in all fees, the loan term, and the total amount you will repay over the life of the loan compared to your current debt.
- Understand the Terms and Conditions: Read the fine print of any loan or agreement. Pay attention to repayment schedules, penalties for late or early payment, and the consequences of default (especially with secured loans where assets are at risk).
- Address Spending Habits: If overspending is an issue, a new loan will only be a temporary fix unless you create and stick to a budget and change your financial habits.
- Seek Professional Advice: Consider speaking to a qualified and independent financial advisor or a registered debt counsellor in South Africa. They can help you understand your options, the implications, and whether a particular loan to pay off debt is the right move for your specific circumstances.
- Compare Offers: If you decide a loan is the way forward, shop around and compare offers from different lenders or through brokers like NH Finance to find the most favourable terms.
Conclusion
Loans to pay off debt can be a highly effective strategy for individuals and businesses in South Africa struggling under the burden of multiple financial obligations. By consolidating debts into a single, manageable repayment, potentially at a lower interest rate, it’s possible to regain control of your finances, reduce stress, and work steadily towards a debt-free future.
NH Finance, as a finance brokerage, offers a diverse portfolio of specialised solutions, particularly for those who can leverage property or other valuable assets. From innovative sale-and-leaseback arrangements for homeowners to tailored loans for businesses in rescue, liquidators, and general loans against property or movable assets, their offerings provide various avenues to address debt.
However, the key to successfully using any loan to pay off debt lies in careful planning, a thorough understanding of the product, a realistic assessment of your ability to repay, and a commitment to sound financial management going forward. With the right approach and the right financial products, the path out of debt can become clearer and more achievable.
Personal Finance
The concept of tax migration, or “financial emigration,” has become increasingly relevant for South Africans moving abroad. As the global landscape evolves, so too do the opportunities for work and life in foreign countries. However, relocating abroad involves more than just packing your bags; it necessitates navigating through the complex process of tax emigration from South Africa to ensure compliance with tax laws and to optimize your financial situation. This guide aims to simplify this process, offering essential insights and steps for South Africans planning to move overseas in 2024.
Understanding Tax Emigration
Tax emigration, formally known as “financial emigration,” is the process of changing your status with the South African Revenue Service (SARS) and the South African Reserve Bank (SARB) from resident to non-resident for tax and exchange control purposes. This doesn’t mean renouncing citizenship but rather reclassifying your tax residency to reflect your move abroad, ensuring you meet all regulatory requirements and potentially optimizing your tax obligations.
The Process of Tax Emigration
The process of tax emigration involves several steps, including declaring your intention to emigrate financially to SARS and ensuring all your tax affairs are in order. It’s crucial to undertake this process meticulously to avoid complications. Seeking professional advice is highly recommended to navigate the complexities of tax laws and exchange controls. For assistance with the financial aspects of emigration, including foreign currency exchange, consider services like those offered by New Heights Finance, which specializes in helping South Africans with tax emigration.
Detailed Steps for Tax Emigration
1. Understanding Your Tax Residency
Before initiating the tax emigration process, it’s crucial to understand what constitutes tax residency in South Africa. South Africa uses a residence-based tax system, where residents are taxed on their worldwide income. Your tax residency is determined by the physical presence test and the ordinarily resident test. Understanding these criteria is the first step in the tax emigration process.
2. Consultation with a Tax Professional
Given the complexities involved, consulting with a tax professional experienced in tax emigration is advisable. They can offer tailored advice based on your specific circumstances, help you understand your tax obligations, and guide you through the process of complying with South African and international tax laws.
3. Settling Your Tax Affairs
Before you can formally emigrate for tax purposes, all your tax affairs must be in order. This includes submitting any outstanding tax returns and paying any due taxes. SARS requires a clear record before processing your emigration, which is crucial for obtaining a Tax Clearance Certificate (TCC) for emigration.
4. Completing the MP336(b) Form
Part of the emigration process involves completing the MP336(b) form, which is a Reserve Bank application. This form is essential for changing your status for exchange control purposes and requires detailed financial information, including a declaration of your assets and liabilities.
5. Tax Clearance Certificate for Emigration
Applying for a Tax Clearance Certificate (TCC) specifically for emigration is a crucial step. This certificate proves that your tax affairs are in order and is required by both SARS and the South African Reserve Bank (SARB) to process your financial emigration.
6. Opening a Non-resident Bank Account
As part of the financial emigration process, you’ll need to convert your South African bank account into a non-resident account. This account is used to manage your South African financial affairs from abroad, including the transfer of funds outside the country under the guidance of exchange control regulations.
FAQs
What is tax emigration in South Africa?
Tax emigration is the formal process of changing your status with SARS and the SARB from a tax resident to a non-tax resident. This is an essential step for South Africans moving abroad to ensure compliance with local tax laws and to manage their tax obligations effectively.
How do I financially emigrate from SARS?
To financially emigrate from SARS, you must ensure all your tax affairs are up to date, submit an emigration application through SARS eFiling, and declare your worldwide assets and income. It often requires a tax clearance certificate indicating all your tax obligations have been settled.
How do I notify SARS of emigration?
You notify SARS of your emigration by submitting a tax emigration application and the necessary documentation through their eFiling system. This includes a declaration of your assets and liabilities, and may also require a formal emigration approval from the South African Reserve Bank (SARB).
What happens if you don’t financially emigrate from South Africa?
Failing to financially emigrate can lead to significant legal and financial implications. You may continue to be taxed on your worldwide income by SARS, face penalties for non-compliance, and encounter difficulties with accessing and transferring funds abroad. It’s crucial to complete this process to avoid these complications and ensure your finances are properly managed according to your new residency status.
What is the difference between tax emigration and physical emigration?
Tax emigration refers to the process of changing your status with SARS and SARB to non-resident for tax and exchange control purposes. Physical emigration is the act of moving to another country. Tax emigration is a legal and financial process, while physical emigration involves relocating your life and possessions.
Can I reverse my tax emigration status?
Yes, it is possible to reverse your tax emigration status if you return to South Africa and meet the criteria to be considered a tax resident again. This process involves re-registering with SARS as a tax resident and ensuring compliance with the relevant tax laws and regulations.
What are the consequences of incorrectly declaring my tax status?
Incorrectly declaring your tax status can lead to significant penalties, interest charges, and legal action from SARS. It’s important to accurately declare your status and fully disclose all required information to avoid these consequences.
Conclusion
Tax migration is critical for South Africans moving abroad, ensuring compliance with tax laws and optimizing financial arrangements in their new country of residence. The process can be complex, involving various legal and financial considerations. However, you can navigate this transition smoothly with careful planning and the right guidance, such as the services offered by NH Finance for tax emigration from South Africa. Ensuring your tax status accurately reflects your residency is not just about legal compliance; it’s a step towards securing your financial future as you embark on your new life abroad.
Frequently Asked Questions
Q: What is tax emigration for South Africans?
Tax emigration is the formal process of changing your status from being a tax resident to a non-tax resident of South Africa in the eyes of the South African Revenue Service (SARS). This process is important for individuals who have left or are planning to leave South Africa to live or work abroad for an extended period.
Q: Why would a South African need to consider tax emigration?
A South African might need to consider tax emigration to avoid being taxed on their worldwide income by SARS. As a tax resident, you are liable to pay tax in South Africa on your global income. By becoming a non-resident for tax purposes, you are only taxed on your South African-sourced income.
Q: What are the criteria for being considered a non-resident for tax purposes in South Africa?
The criteria involve not meeting the requirements of the physical presence test and/or ordinarily resident test. Essentially, if you are physically absent from South Africa for a certain period or you no longer consider South Africa your true home, you may qualify as a non-resident for tax purposes.
Q: How does one formally undergo the process of tax emigration with SARS?
The process typically involves declaring your non-residency status to SARS through your tax returns, along with providing evidence of your emigration. This might include documentation related to your employment overseas, residency status in another country, and evidence of a new home abroad. It’s advisable to consult with a tax professional to ensure all necessary documentation is properly prepared and submitted.
Q: Are there any tax implications or obligations after completing the tax emigration process?
After completing the tax emigration process, you will only be taxed on your South African-sourced income. However, it’s important to be aware of exit charges, such as Capital Gains Tax (CGT), which is often referred to as an “exit tax”. This tax is applicable to your worldwide assets, treating them as if they were disposed of at market value on the day before you cease to be a tax resident.
Q: Can a tax emigrant still own property in South Africa?
Yes, a tax emigrant can still own property in South Africa. However, rental income from that property, or any other South African-sourced income, will still be subject to South African tax, albeit potentially at different rates or with different exemptions than those for residents.
Q: What is the difference between financial emigration and tax emigration?
Financial emigration is a process with the South African Reserve Bank (SARB) and relates to your status for exchange control purposes, whereas tax emigration relates to your status with SARS for tax purposes. While related, these processes are distinct and have different implications for your financial and tax affairs.
Q: Is it possible to reverse tax emigration?
Reversing tax emigration is possible if you return to South Africa and meet the criteria to be considered a tax resident again. This would involve re-establishing your economic and personal ties to South Africa and potentially passing the ordinarily resident or physical presence tests.
Personal Finance
A legacy is something passed down from a predecessor to a future generation. There are many ways to leave a personal legacy. Regardless, one of the most powerful legacies you can leave is a financial legacy.
It’s pretty common for people to defer thinking about legacy planning till when they are approaching old age. It is a well-known fact that death is a reality and one never knows when it’s their time. Though it is discomforting to think about dying it is equally important to have a plan in place in the event of your death.
No matter how much you are worth, legacy planning is an important part of your overall financial and retirement planning and it’s never too early to get your affairs in order. Read on for four important steps to get organized and leave a lasting financial legacy.
1. Take a Personal Inventory
Having accumulated all kinds of assets and other things over the years it is crucial you make a list that accounts for all your belongings from your home to your personal items. This is usually the first step in getting organized so as to ensure you are not forgetting and leaving out anything of immense value.
2. Life Insurance
Life insurance protects you and your loved ones from the financial uncertainty of death or severe illness or disability. Getting life insurance is a cost-effective way of ensuring the financial security of your family or beneficiaries in the event of your passing. This is important if you have children or other family members who are dependent on you for financial support. It will provide an income for them in the event of your untimely death. If you have one already, do ensure that your beneficiaries are up-to-date and listed correctly.
3. Prepare a Will and Testament
Having a will is a significant step in securing the financial future of your loved ones. A Will is a legal document that coordinates the distribution of your assets and wealth after your death. A Will declares who the beneficiaries of your assets are and how your assets should be distributed. Having a Will protects your family or loved ones and makes it much easier to sort everything out when you die. In the absence of a Will, the process can be time-consuming and stressful as assets will be distributed according to state laws and the courts.
If you are yet to put your will together, get in touch with us for assistance over here.
4. Select The Right Estate Administrator
Your estate administrator or executor manages and administers your Will when you die. As such it is essential that you select an individual who is trustworthy, reliable and responsible. Many people appoint an executor such as their spouse or child without giving it much thought. To ensure your wishes are followed it makes sense to consider carefully who’s best suited for it.
Bottom Line
Putting your affairs in order can be a difficult thing as no one likes to think about dying. Nevertheless, failure to put a plan in place can make life difficult and strenuous for your loved ones.
Personal Finance
Doctors and hospitals are there to provide medical care and life-saving interventions for patients, but unfortunately sometimes things go wrong. This is particularly true for government hospitals in South Africa where standards of care, hygiene and equipment are below what is acceptable. While doctors simply cannot prevent negative outcomes for every single patient, they are required to adhere to a strict code of ethics and standards of practice to prevent putting patients at risk.
Who do you submit a medical negligence claim to?
If you have been a victim of medical negligence by a doctor or hospital, you will open a civil case at the High Court to claim for damages. You will either be suing a doctor or a hospital. When suing a hospital, the hospital or State (if a government hospital) are held liable for the negligence of staff employed by the hospital.
What constitutes medical negligence?
- the healthcare provider or hospital was legally responsible for providing the patient with care
- the healthcare provider or hospital breached their obligation to provide a level of care that meets regulatory standards
- the breach in care resulted in serious injury or death to the patient
- the injury to the patient resulted in financial loss and emotional trauma
Common cause for claims include:
- inadequate patient records
- failure to disclose risks to the patient
- failure to follow correct treatment protocols at the correct time
- poor monitoring of patient (development of infections, worsening condition, secondary health issues, death)
- birth injuries
When are you legally able to submit a medical malpractice claim?
When you sign your admission forms, you often sign an indemnity or disclaimer thus waiving your right to sue the healthcare provider or hospital by knowing all the associated risks. However, if the above misconduct causes can be proven, you have a good chance of opening a case against the healthcare providers or hospital.
How soon must you make a medical negligence claim?
You must submit a medical negligence claim within three years of the incident occurring.
Damages you can claim for
- Medical expenses
- loss of income
- compensation for chronic pain, emotional trauma and suffering
if you need to sue a doctor or hospital we are able to connect you with a medical malpractice attorney. If your medical negligence claim has been approved, we can also give you an early cash advance while you await payment.
Personal Finance
South Africans have always experienced tougher economic conditions than other countries so its no wonder we are savvy when it comes to saving money. With economic conditions being tougher than ever before, many South Africans are cutting back on their expenses in order to save money and make it through the month. In fact, 55% of all households are still bearing the brunt of the strain the Cover-19 pandemic have put on their finances.
Here is a list of the top expenses South Africans cut back on in 2023:
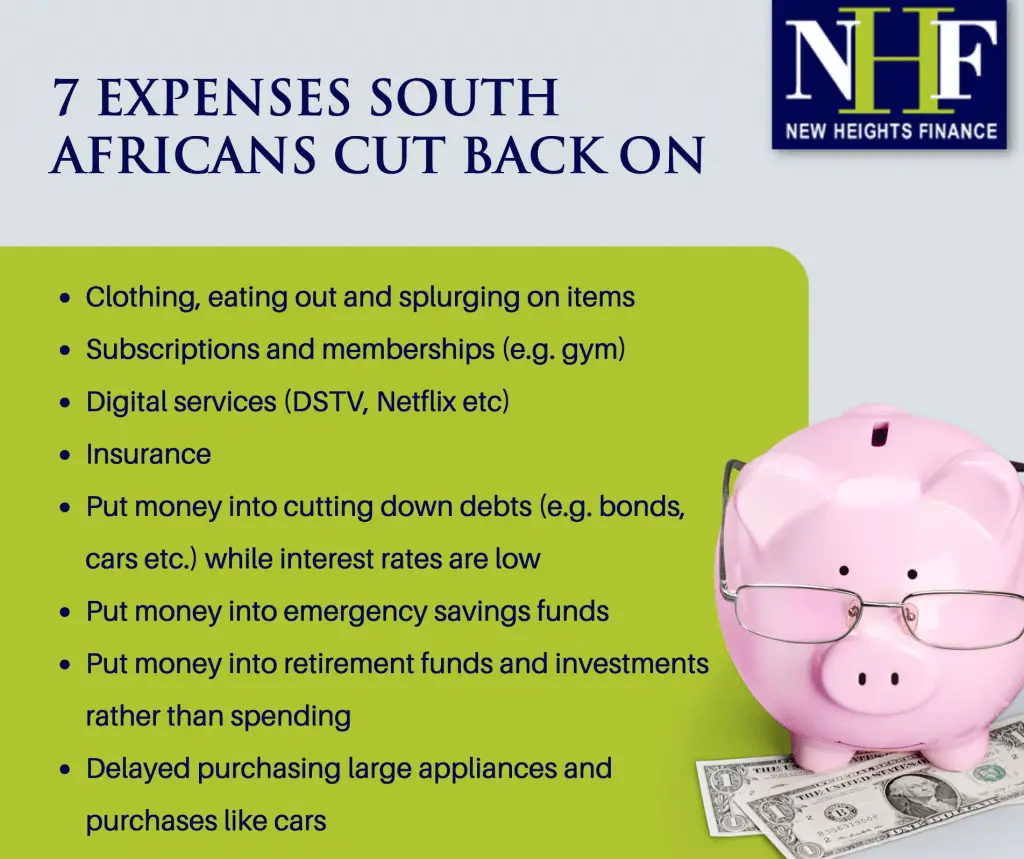
Most consumers have cut back on luxury and big-ticket purchases like appliances, cars and luxury brands, delaying the purchases until their personal finances recover. They have also cut back on subscriptions and memberships like gym and mobile phone contracts.
On the flip side, households have put more money into emergency savings funds, into cutting down debt and into retirement funds. 85% of households are very concerned about how they will manage to pay their bills and debts going forward if things don’t improve.
If you find yourself in a real financial bind and need access to cash quickly, apply for one of our loan solutions today:
Personal Loans –got a clear credit record and need up to R150k fast? Apply for a personal loan.
Pension Bridging Loans – waiting for your pension or provident payout? Apply for a pension cash advance and get some of your money early to ease financial stress.
Loans Against Assets – use art, jewellery, handbags and luxury items as security for a secured personal loan. Get them back once your loan is paid up.
Loans Using Un-bonded Property – is your property valued at over R2 million and fully paid up? Use your home as security for an equity release loan of R1 million or more.
Personal Finance
When we rang in the New Year, who would have guessed we would face a global pandemic that would creep into every country and continent across the world. That some of us would lose businesses, lose our jobs or take massive salary cuts. We are living in extraordinarily difficult times.
The business gurus and commentators say there is a new ‘normal’ we all need to get used to which includes working from home, working in shifts or teams and often as a result, reduced hours. Unfortunately, this new way of doing business has resulted in company retrenchments, dismissals and forced resignations across almost every industry, with some being harder hit than others. As of today, hair & beauty salons, restaurants, certain manufacturing concerns and gyms to name a few can only operate under reduced capacity and with major restrictions in place. Many businesses have been unable to bring in an income since lockdown in South Africa started on 26 March 2020.
When faced with this situation, UIF registered employees can claim from the Unemployment Insurance Fund. The problem with UIF is that it does not pay out the full wage or salary. This leaves an income shortfall. Families expenses are generally fixed and there is very little opportunity to reduce monthly living costs. For example: school fees, rent, bond repayments and food are all fixed costs.
The good news is that there are a number of temporary financial solutions available to the public:
1. Pension Loan
If you have given notice to your pension fund or provident fund that you want to make your policy paid up, it is possible to secure a short- term Pension Bridging Loan from accredited private lenders.
2. Property Secured Loan
If your home is bond-free or has a bond that is less than 40% of the property value, it is possible
to secure a Loan Against the Property in some circumstances, to help you free up cash to cover expenses.
3. Loan Against a Movable Asset
It is possible to use your valuables like gold, diamonds, art, antiques, jet skis, cars, bakkies, motorbikes and other loose assets, as security for a loan.
When faced with the daunting prospect of retrenchment, do not panic. There are temporary financial solutions that enable families to make it through the tough times. For more ideas and financing solutions click here: www.nhfinance.co.za
